Business Owners Policy: Bop Insurance Package Combining General Liability And Property Coverage For Small Businesses
Picture this: You’re mid-afternoon, sipping a flat white in your boutique coffee shop, when a customer trips over your new reclaimed-wood plant stand. Your latte art is perfec...
Picture this: You’re mid-afternoon, sipping a flat white in your boutique coffee shop, when a customer trips over your new reclaimed-wood plant stand. Your latte art is perfect. Your vibe is impeccable. But now you’re staring at a potential lawsuit over a broken ankle and a bruised ego.
Welcome to the reality of running a small business—where the line between a great day and a disaster is sometimes just a misplaced shoelace. That’s exactly where a Business Owners Policy, or BOP, steps in like a cool-headed friend who knows the bouncer’s name.
What’s Actually In the Box?
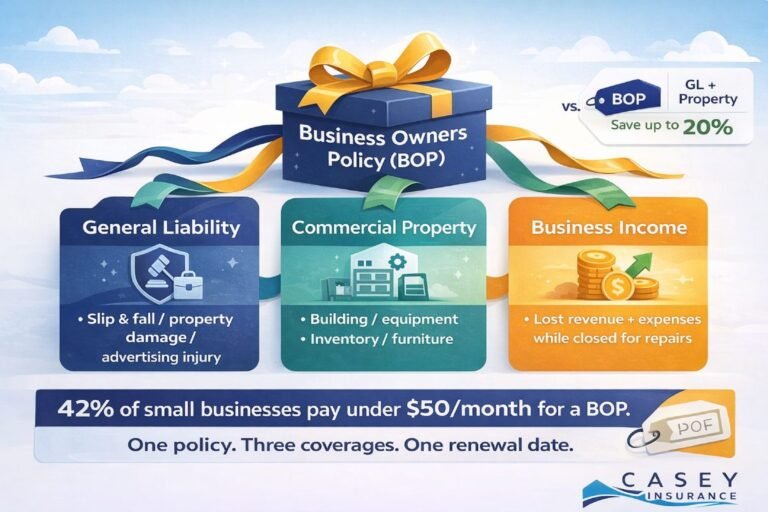
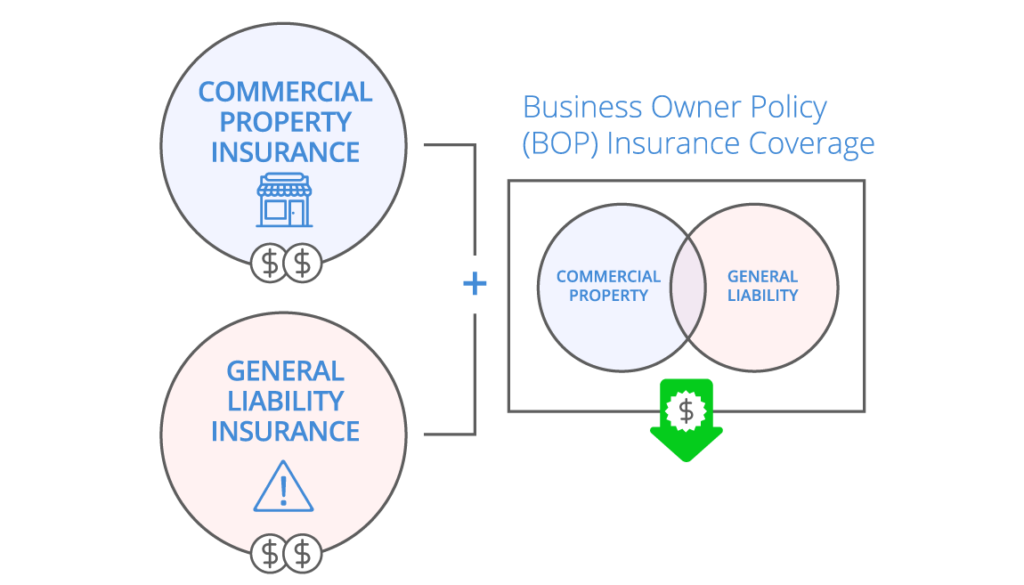
A BOP insurance package isn’t some bureaucratic mystery box. It’s a streamlined bundle that combines general liability and property coverage into one tidy, budget-friendly policy for small businesses.
Must Read
Think of it as the Swiss Army knife of insurance: it handles the basics, so you don’t have to cobble together separate policies like a DIY IKEA project gone wrong. General liability covers those “oops” moments—like the coffee spill on a laptop—while property coverage protects your stuff: your espresso machine, your vintage display cases, even your laptop that’s dangerously close to that same coffee cup.
General Liability: Your Drama Shield
General liability is your first line of defense against the everyday chaos of human interaction. It covers bodily injury—like that tripped customer—and property damage you accidentally cause to others, like scratching a client’s car with your delivery van.
It even handles personal and advertising injury, which is a fancy way of saying “accidental slander.” Did your Instagram post accidentally call a competitor’s bagels “sad and chewy”? Liability’s got your back, not your bad taste.
 What is Business Owner's Policy (BOP) Insurance?
Property Coverage: Keeping Your Kingdom Safe
This part of the BOP protects your physical assets: the building you lease, the inventory you stock, and the equipment you rely on. If a pipe bursts during a snowstorm—or, more likely, a rogue employee blasts the AC too high—property coverage pays for repairs and replacements.
Fun fact: Water damage is the second most common small business claim, right after slip-and-falls. So yes, that office dartboard near the sprinkler system is a liability waiting to happen.
Who Actually Needs a BOP?
If you run a small to mid-sized business with a physical location—a bakery, a yoga studio, a graphic design firm, or even a mobile pet grooming van—this is your sweet spot. Freelancers and home-based businesses often qualify too, as long as you don’t own a skyscraper or run a nuclear reactor.
Pro tip: BOPs aren’t for everyone. If you’re a solo consultant with zero inventory and a rented desk, you might get away with a simple liability policy. But if you have stuff—and a willingness to interact with the public—a BOP is your financial love language.
 Police Business Insurance
What It Doesn’t Cover (The Fine Print)
Here’s where the honesty kicks in: a BOP is not an all-you-can-eat buffet. It doesn’t cover professional errors (you’ll need Errors & Omissions insurance for that), workers’ compensation, or cyber attacks.
If a hacker steals your client list and posts it on Reddit, your BOP says, “Not my department.” For that, you want a standalone cyber policy—think of it as a digital bouncer for your data.
Mixing Insurance with Real Life
Imagine you’re running a pop-up vintage clothing shop. Your friend’s kid spills juice on a rare 1980s jacket. General liability covers the juice, property coverage covers the jacket. Without a BOP, you’d be paying out of pocket for both—and maybe losing a friendship.
Or think of the Great Spring Break Flood of 2023, when a broken pipe ruined a baker’s flour supply. Her BOP didn’t just pay for the flour; it covered lost income while she rebuilt. That’s the difference between a temporary hiccup and a closing sale.
 Business Owners Policy (BOP) | Fortify Group - Insurance & Real Estate
Three Practical Tips Before You Sign
First, check the property limits. Make sure your policy covers replacement cost, not just “actual cash value.” That vintage espresso machine may be worth $5,000 on the market, but after depreciation, the insurance might only give you $500. Not cool.
Second, ask about business interruption insurance. Many BOPs include this as a standard feature, covering lost income if a covered disaster forces you shut down temporarily. It’s like a nap for your bank account while you recover.
Third, don’t over-insure. A BOP is designed for small businesses, so if your inventory is worth $1 million, you need a commercial package policy, not a BOP. Know your limits—literally.
The Cultural Vibe Check
In the Friends universe, Monica’s restaurant, Javu, would absolutely need a BOP. That exploding duck in the kitchen? Property coverage. The time a customer tripped over her mop? Liability. Even Ross’s dry-cleaning mishap would be covered.
 What Is a Business Owners Policy: Explained
In real life, 40% of small businesses face a property or liability claim each year, according to the Insurance Information Institute. That’s roughly the same odds as your favorite coffee shop running out of oat milk—only way more expensive.
Reflection: The Quiet Confidence
At the end of the day, a BOP isn’t just paperwork. It’s the quiet confidence that lets you focus on what you love—baking bread, designing logos, or sweeping vintage vinyls—instead of worrying about a leaky roof or a clumsy customer.
It’s like having a spare key to your house: you hope you never need it, but when you do, it feels like a superhero landing in your driveway. So go ahead, pour that flat white, laugh at your own mistakes, and know that a BOP is the safety net woven into your small-business dream.
Because the best days aren’t just accident-free—they’re fear-free.
