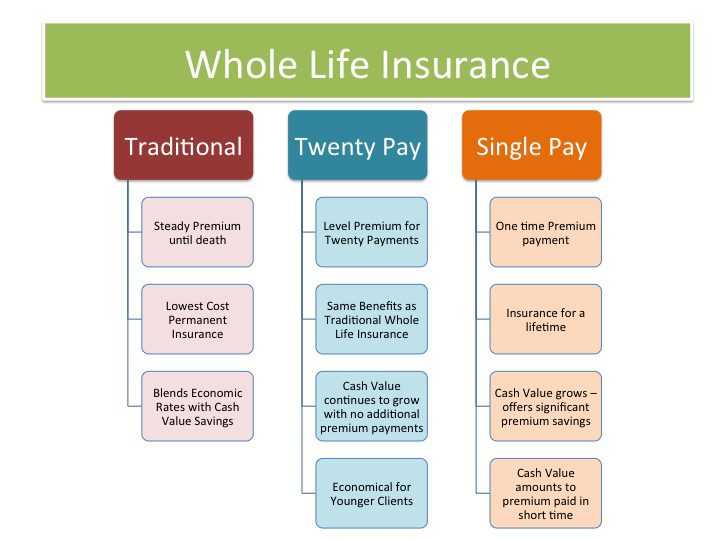
Whole Life Insurance Policy: Permanent Life Insurance With Fixed Premiums, Guaranteed Death Benefit And Cash Value Growth
So, you’ve heard the term “whole life insurance” and instantly pictured a dusty financial binder and a guy in a beige suit. Let’s be real: insurance isn’t exactly the life of...
So, you’ve heard the term “whole life insurance” and instantly pictured a dusty financial binder and a guy in a beige suit. Let’s be real: insurance isn’t exactly the life of the party. But what if I told you there is a financial product that acts like a stubborn, undying pet tortoise that also happens to stash cash under its shell? Welcome to the wild world of Whole Life Insurance.
The “Set It and Forget It” Philosopher
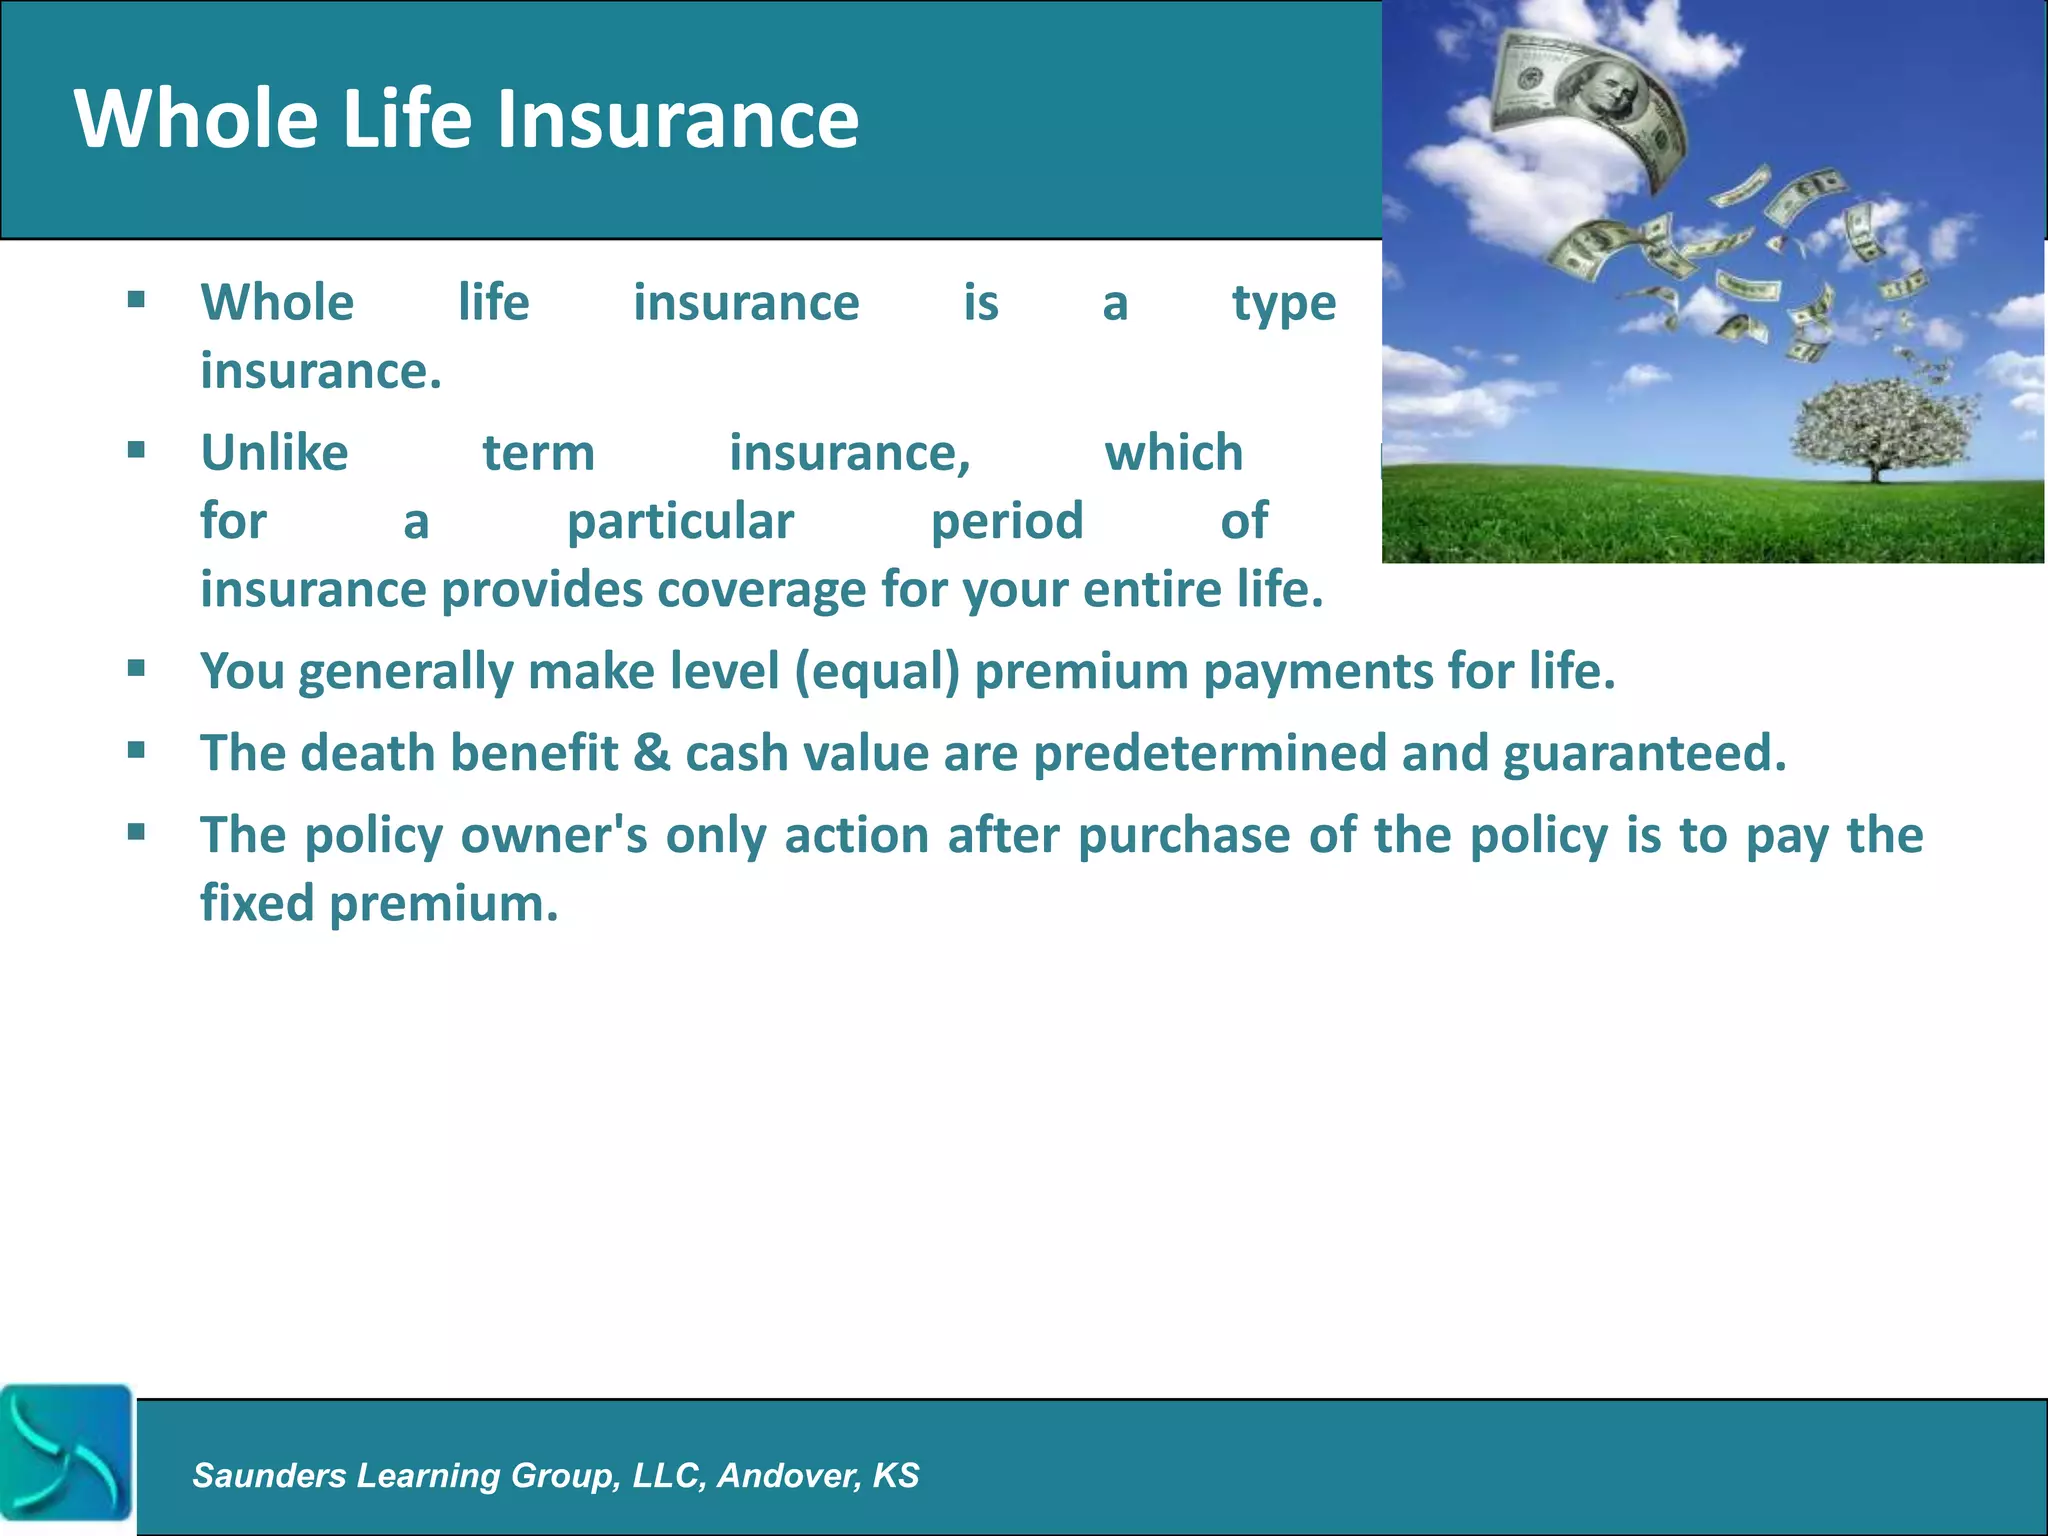
Unlike term life, which is like renting a tuxedo—you use it for a while and then it vanishes—whole life is permanent. You sign up, and this policy sticks with you like gum on a hot sidewalk. The core deal is brutally simple: you pay a fixed premium every month for the rest of your life (or until you hit a paid-up status, you overachiever).
In return, the insurance company makes you a rock-solid promise. They will pay a guaranteed death benefit to your loved ones, no matter if you kick the bucket at age 47 or 97. It’s like a cosmic “I.O.U.” that doesn’t expire, which is surprisingly rare in a world where yogurt expires, fashion expires, and even your gym membership mentally expires.
Must Read
The Cash Value: Your Policy’s Secret Savings Account
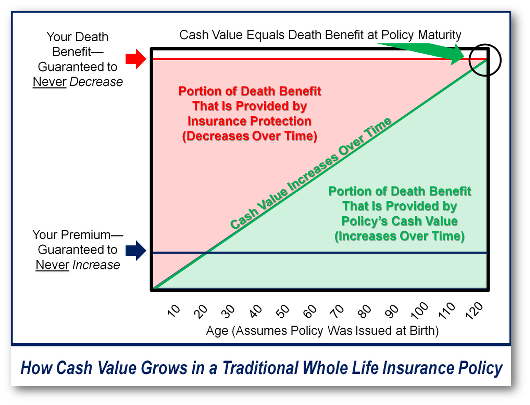
Here’s where it gets juicy. Part of your premium doesn’t just pay for the death benefit and the company’s fancy coffee machine. It goes into a tax-deferred cash value account. Think of it as a tiny, legal piggy bank that grows inside your policy. Over time, this cash value grows at a guaranteed rate, although the insurer will call it “modest” while you call it “slower than a snail on valium.”
But wait, there’s more! You can actually borrow against this cash value. Need a down payment on a llama farm? A last-minute trip to Vegas? You can take a loan from yourself—which sounds Kafka-esque but is actually legal and surprisingly convenient. The catch? If you die before paying it back, the insurance company deducts the loan from your death benefit. So, don’t die while driving your new llama-mobile with the stereo blasting.
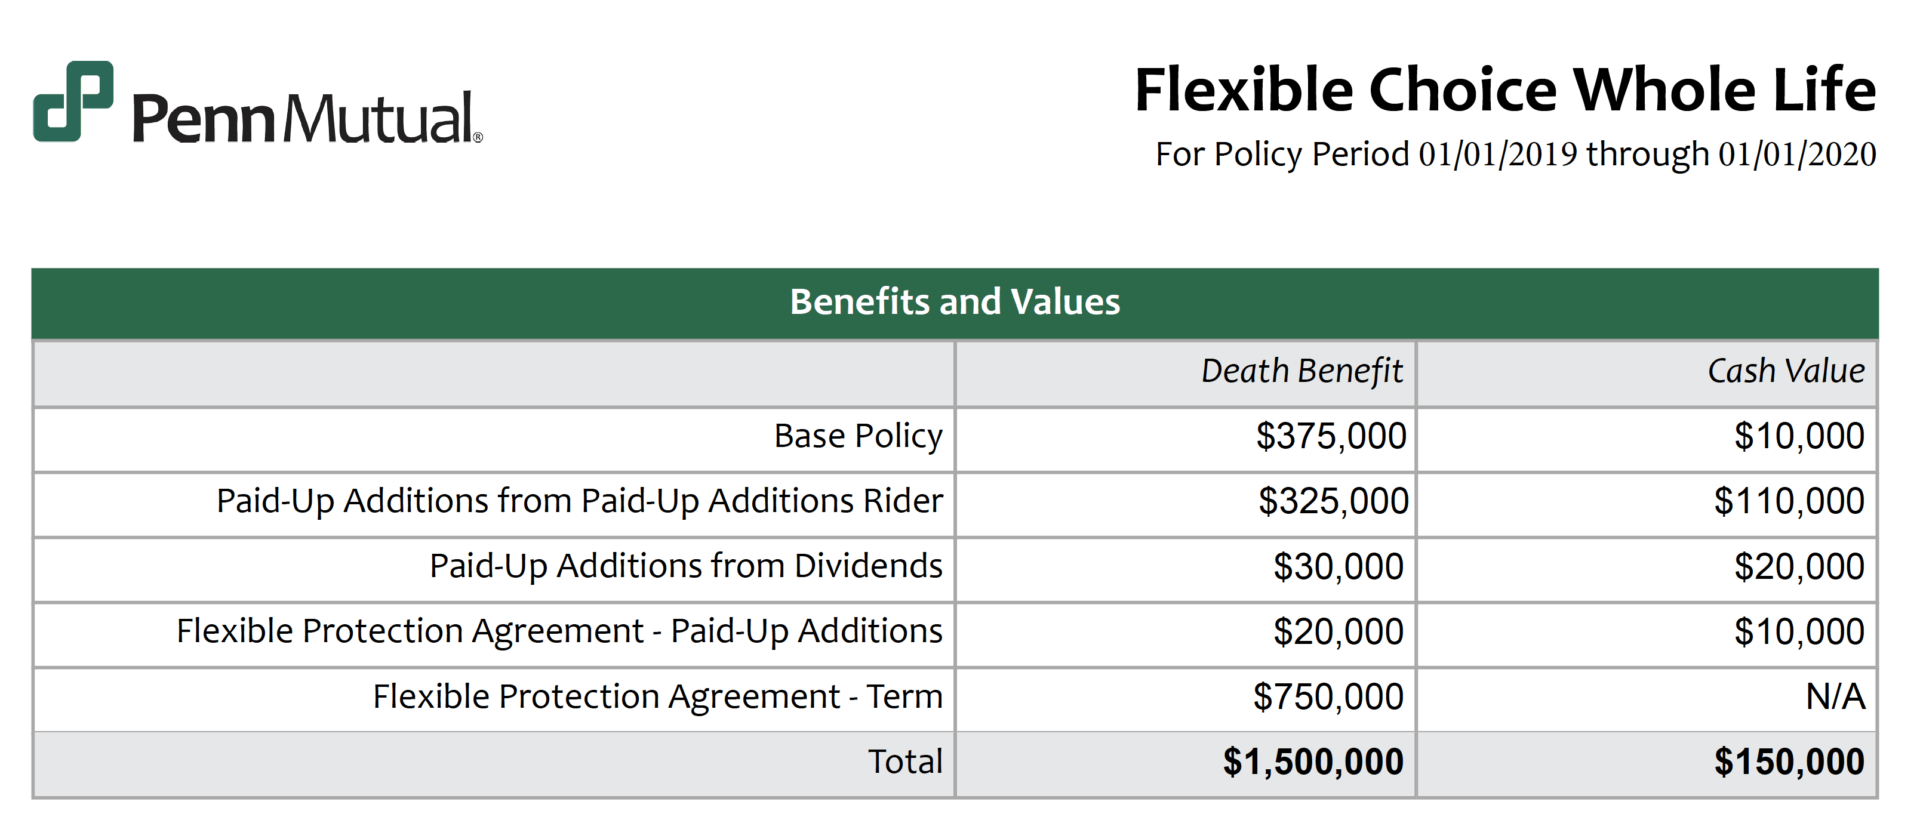 How to Read and Understand your Whole Life Insurance Statement • The
The Guarantees: Boring But Beautiful
Let’s talk about the “guaranteed” part, because it’s the whole reason this product exists. Your death benefit is guaranteed to stay the same (unless you mess with it). Your premiums are guaranteed to never go up—even if you take up skydiving while juggling chainsaws. This is a big deal, because in the world of finance, “guaranteed” is about as common as a unicorn at a dog park.
And here’s a surprising fact: the cash value growth is also guaranteed, usually around 2% to 4% depending on the policy and the year. That’s not Bitcoin-level excitement, but it’s also not “oops, my 401k just did the limbo with a greased stick.” It’s the slow, steady, boring friend who always shows up with a casserole. And honestly, sometimes you need the casserole friend.
The Fine Print: Where Dreams Go to Get a Papercut
Okay, let’s be real. Whole life is expensive. Like, “why did I just buy a small car in monthly payments?” expensive. The fixed premium is high because you’re paying for a lifetime of coverage and stuffing that cash value piggy bank. If you compare the death benefit cost alone, term life is a bargain basement sale, while whole life is the designer handbag you justify by saying “it’s an investment.”
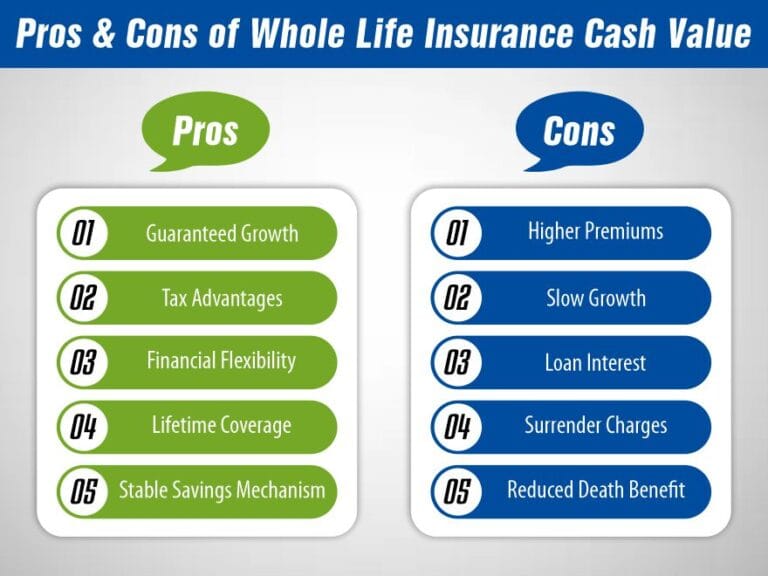 How Whole Life Insurance Builds Cash Value Over Time
Also, the cash value grows slowly at first. In the first few years, most of your premium goes to fees and commissions. It’s like paying for a gym membership and only lifting the pen to sign the contract. Patience is not just a virtue here; it’s the whole game. You have to hold this thing for a decade or more before the cash value seriously starts to bulk up.
Who Is This For? (Spoiler: Probably Not You, Unless…)
Whole life isn’t a secret handshake for the ultra-rich. It’s actually great for people who want a certain, boring, predictable legacy. Think: someone with a special needs child who needs guaranteed lifelong support, or someone who hates volatility more than a cat hates a bath. If you have maxed out your 401(k), IRA, and you’re still itching for a tax-advantaged savings bucket, this is your weird, nerdy friend.
 Life insurance basics | PPTX
But for most folks? You’re better off buying term life and investing the difference in a stock market index fund. That strategy is like a rocket ship compared to whole life’s tricycle. However, if you want absolute certainty that your death benefit will be there even if the market crashes into a black hole, whole life is your financial safety blanket.
The Punchline: It’s a Financial Oddball
Whole life insurance is the mullet of financial products: business in the front (guaranteed death benefit), party in the back (cash value you can borrow). It’s slow, it’s weird, and it hates being called boring. But for the right person, it’s a masterclass in stubborn financial discipline. You lock in the premium, you ignore the shiny new stocks, and you wait. And wait. And one day, you look at your cash value, smirk, and realize you’ve been slowly winning the whole time.
Just don’t lend your policy to your cousin Gary. He’ll try to use the cash value to start a glow-in-the-dark pet rock business. Trust me on this.