Iul Policy: Indexed Universal Life Insurance Combining Death Benefit With Cash Value Tied To Stock Market Index
So, you’ve finally admitted it. You’re not getting any younger, and that little voice in your head is starting to whisper about "retirement" and "legacy." It sounds about as f...
So, you’ve finally admitted it. You’re not getting any younger, and that little voice in your head is starting to whisper about "retirement" and "legacy." It sounds about as fun as re-organizing your garage, right?
Well, hold onto your 401(k) statements, because there’s a financial product out there that sounds like it was made for people who want to have their cake and eat it too. I’m talking about the Indexed Universal Life policy, or IUL as the cool kids in the breakroom call it.
Think of it as the Swiss Army knife of insurance. It’s trying to be a death benefit for your family, a savings account for you, and a stock market cheerleader all at once. Does it sound too good to be true? Maybe. But let’s unpack this weird, wonderful, and slightly confusing beast.
Must Read
The "Why Didn’t I Think of That?" Part
Imagine you’re a squirrel. You need to stash nuts for the winter (that’s your cash value). But you also want to be a cool squirrel who invests in the local acorn market. The problem? The market goes up and down like a yo-yo on caffeine.
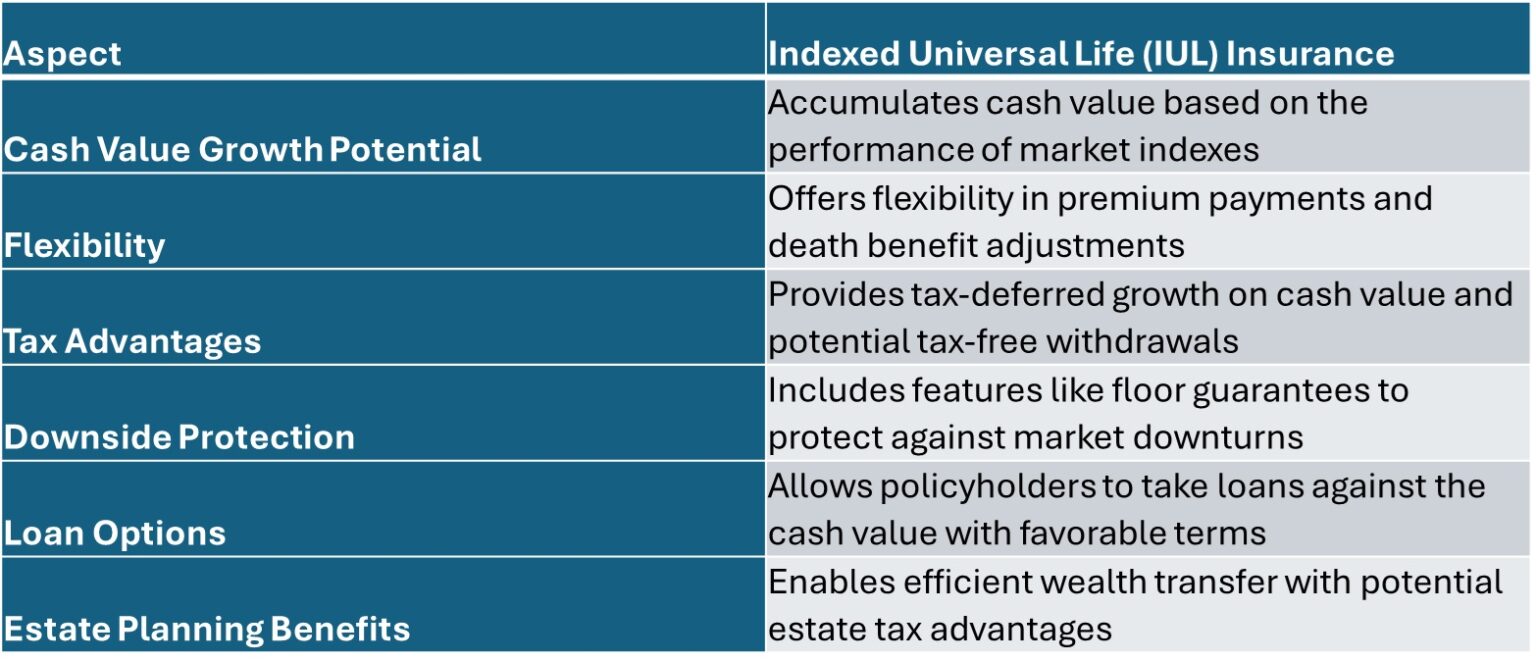
An IUL says, "Hey, squirrel, I’ll protect your stash from crashing. I’ll cap your gains, but you won’t lose a penny when the market tanks, as long as you pay your premiums." It’s like having a safety net made of marshmallows and a parachute made of hopes and dreams.
 Indexation in Life Insurance: How Do You Index Link a Policy?
The key is that your cash value is tied to a stock market index, like the S&P 500. But it’s not invested directly. It’s more like you’re betting on the index’s performance, with a fancy "floor" that stops the bleeding if things go south.
The Good, The Bad, and The "Huh?"
Here is where your everyday life kicks in. Remember that time you bought a lottery ticket and felt rich for about ten minutes? An IUL is nothing like that. It’s more like a steady, slightly boring friend who shows up with a boring gift that turns out to be a gold bar.
The good part is the tax-deferred growth. Your cash value grows without Uncle Sam licking his fingers and taking a bite every year. You can also take loans against it, tax-free, for things like buying a boat (or, you know, paying for tuition). That’s the stuff dreams are made of.
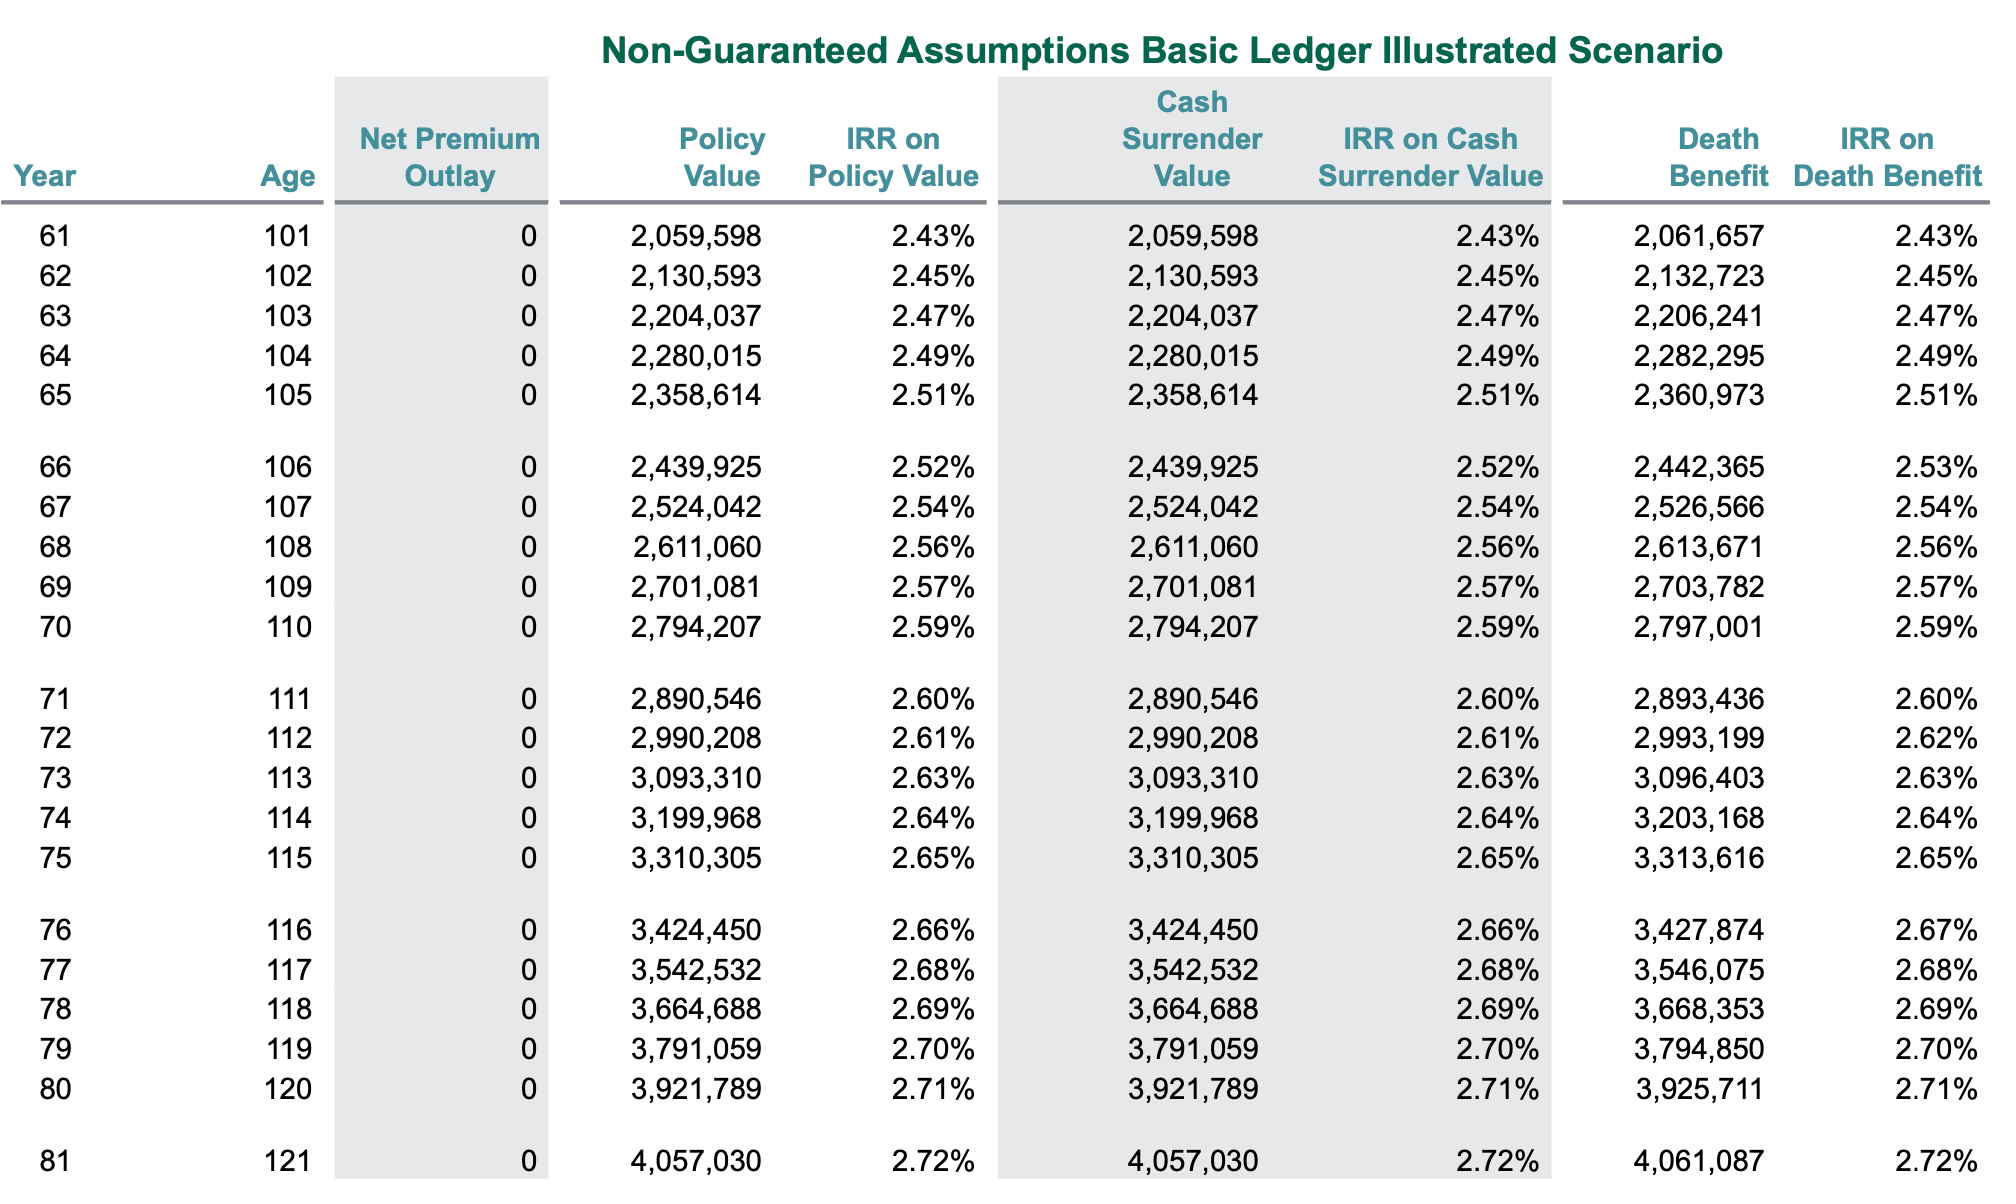 Stress Testing Indexed Universal Life Insurance • The Insurance Pro Blog
The bad part? It’s complicated. Very complicated. The fees can be sneaky, like that one friend who always “forgets” to pay for their share of the pizza. You’ll see terms like "cap rate," "participation rate," and "spread," which sound like fast food options but are actually math equations.
And the "huh?" part is the cap. When the stock market climbs 20% in a year (congrats!), your IUL might only credit you 8% because of that cap. It’s like your boss saying, "Great work, but we only give raises up to a certain dollar amount." Still, 8% is better than zero, especially when your neighbor lost money in crypto.
The "Is This For Me?" Test
Are you the kind of person who likes to plan, but also likes to not stress about every dip? Do you want a death benefit that protects your family, but also a side of "maybe I’ll have cash later"? You might be an IUL candidate.
 What Is A Fixed Annuity How Do They Work And Why Are They Important
Picture this: You’re 45. You’ve got a mortgage, two kids who eat like horses, and a dog that thinks the couch is a chew toy. Life is a beautiful mess. An IUL is like having a backup plan for your backup plan.
It’s not a get-rich-quick scheme. It’s a get-slowly-steady-and-slightly-smug scheme. You won’t become a millionaire overnight. But you also won’t be eating cat food in a retirement home because the market crashed twice.
The Punchline
Let’s be real: Most financial products are as exciting as watching paint dry. But an IUL has a certain charm. It acknowledges that life is uncertain. You might get hit by a bus (death benefit). Or you might live to 95 and need cash for shuffleboard (cash value).
 The Doomed Index Universal Life Insurance Policy • The Insurance Pro Blog
The smartest thing you can do is not buy one based on a funny article you read on the internet. Talk to a financial advisor who won’t laugh at your recent crypto losses. Ask them to draw you a picture. A simple one.
But if you do end up with an IUL, just remember: you’re basically buying a insurance policy that moonlights as a cautious stock trader. It’s weird. It’s complicated. And sometimes, it’s exactly the weird, complicated thing that makes you sleep better at night.
Now, go forth and be a responsible adult. Or at least, pretend to be one while your IUL does the heavy lifting. Maybe you can have your cake and eat it too. Just don’t forget to read the fine print, because those little words are where the cake hides all the calories.
