Life Insurance Policy: Contract Providing Death Benefit To Beneficiaries In Exchange For Premium Payments
Let’s be honest: life insurance sounds like something your accountant whispers about at a dinner party—right before the dessert course. But peel back the jargon, and it’s real...
Let’s be honest: life insurance sounds like something your accountant whispers about at a dinner party—right before the dessert course. But peel back the jargon, and it’s really just a financial hug for your people. You pay a little now so they get a lot later, no strings attached.
Here’s the core deal: a life insurance policy is a contract between you and an insurer. You agree to pay premiums—think of them as a subscription for peace of mind—and in return, the company promises a death benefit to your beneficiaries when you’re no longer around. It’s the ultimate “after I’m gone, the fridge stays stocked” move.
Now, that benefit can cover everything from a mortgage to your kid’s tuition. It’s not a spooky thought; it’s a strategic one. You’re essentially saying, “I’ve got your back, even from the next zip code.”
Must Read
Two Flavors of Coverage (Spoiler: One’s Not Sexy, but It Works)
Most policies fall into two camps: term and permanent. Term insurance is like renting an apartment—you pay for a set number of years (10, 20, 30), and if you die within that window, the payout triggers. It’s cheap, simple, and perfect for covering temporary gigs like raising kids or paying off debt.
Permanent insurance, on the other hand, is like owning a home. It lasts your entire life (assuming you keep paying) and even builds cash value over time, which you can borrow against. Think of it as a life plan and a piggy bank rolled into one—just don’t expect to break the bank overnight.
Fun fact: the first modern life insurance policies appeared in 17th-century London, sold in coffeehouses by merchants who basically gambled on your life. Today, we call it actuarial science; back then, it was caffeine and a coin flip.
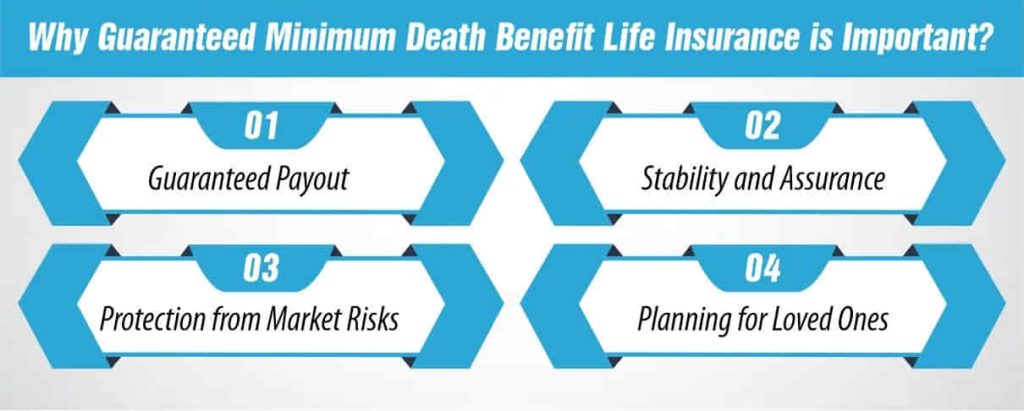 Guaranteed Minimum Death Benefit Life Insurance Coverage
Your Beneficiaries: The VIPs of the Contract
Who gets the money? That’s where beneficiaries come in—usually your spouse, kids, or a trust. You can name multiple people and even specify percentages (60% for your partner, 40% for that one cousin who always brings dessert).
Here’s a practical tip: always designate a secondary beneficiary. Why? If your primary picks pass away before you, the payout could get stuck in probate court—a bureaucratic black hole you want to avoid. Update your list after major life events, like a marriage or a new baby.
One cultural nod: in the Simpsons, Homer famously takes out a policy on Bart’s life after a near-death experience. It’s funny, but in real life, you can insure anyone you have an “insurable interest” in—like a business partner or a parent. Just leave the cartoon pranks out of it.
Premium Payments: The Price of the Promise
Your premium is calculated based on your age, health, and lifestyle—smokers, you’ll pay more (it’s not a moral judgment, just math). The younger and fitter you are, the cheaper the rate. Think of it as a gym membership that actually pays off if you ditch the doughnuts.
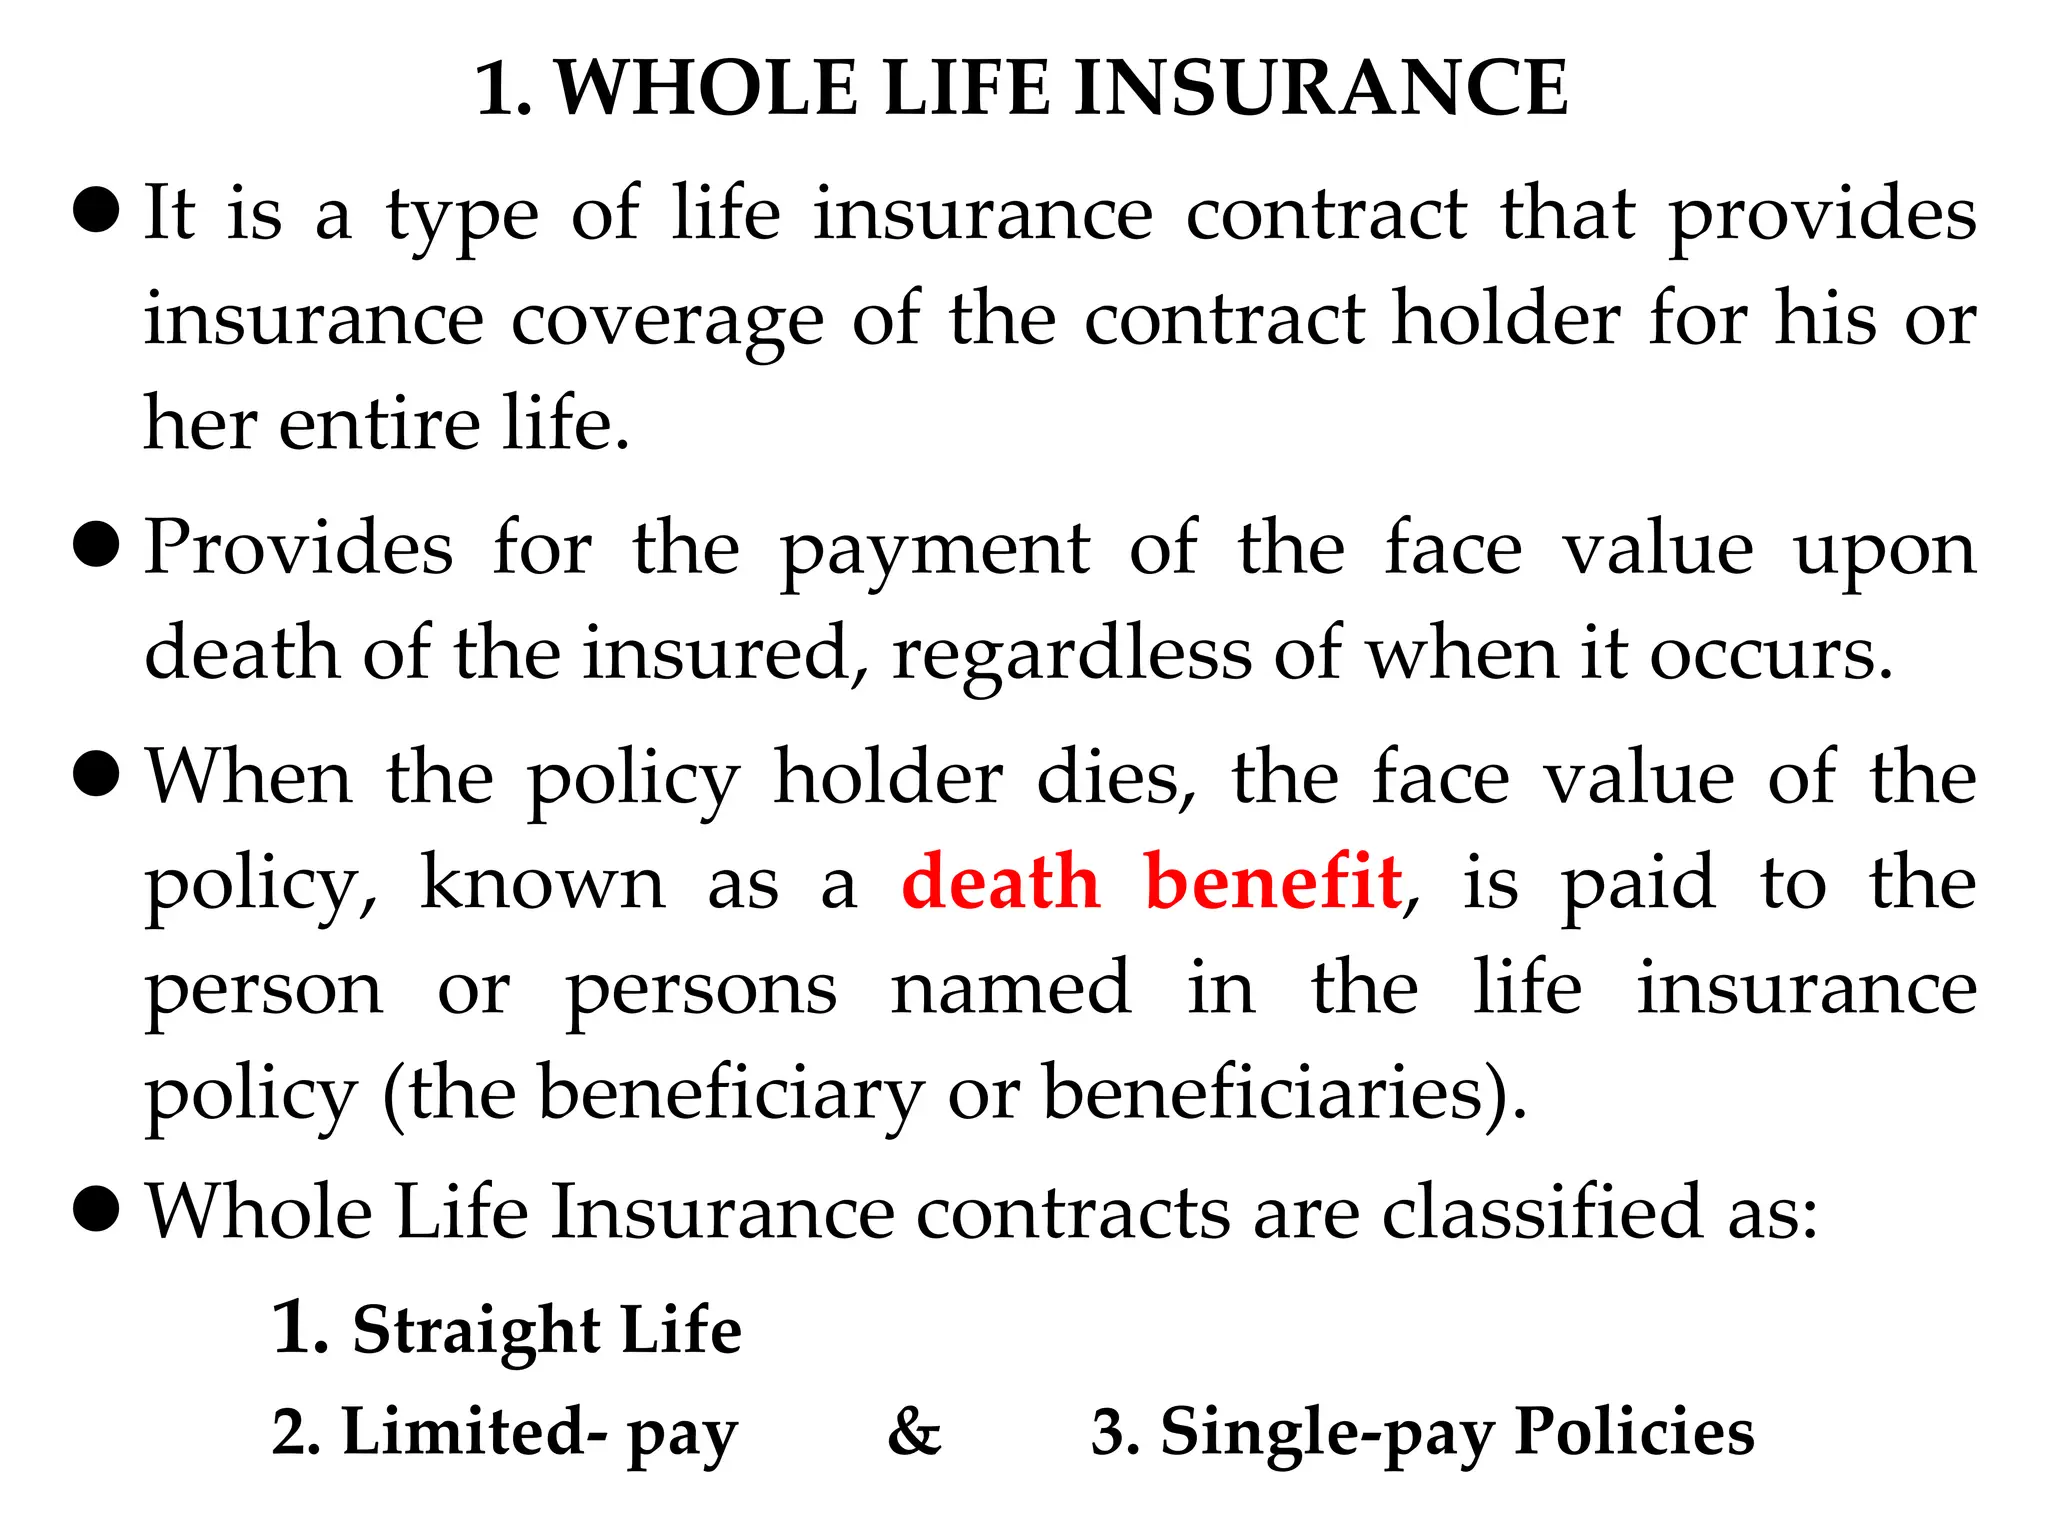 RISK CHAPTER 5.ppt risk management of 55 | PPT
Fun fact: Jeffrey Bezos once said life insurance was the first financial product he ever bought, right after starting Amazon. If one of the richest people on Earth thinks it’s a good idea, you probably can, too. (Hint: you don’t need to own a billion-dollar company to get started.)
Pro tip: pay your premiums annually instead of monthly. Insurers often give a small discount—like 5%—for lump-sum payments. It’s not a massive windfall, but it’ll save you enough for a nice dinner or a couple of lattes.
When the Contract Kicks In (It’s Not as Grim as It Sounds)
When you pass away, your beneficiary files a claim with the death certificate. The insurer then pays the benefit—usually within 30 to 60 days. The money is income-tax-free, which is a huge win. No IRS share, just straight-up support for your loved ones.
 Death Benefit | AwesomeFinTech Blog
What if you live past the policy’s term? On a term policy, you just stop paying, and coverage ends. It’s like an expired coupon—no value, no drama. But if you go with permanent insurance, the cash value grows, and you can even surrender it for a lump sum later in life.
A fun cultural reference: Willy Wonka once said, “We are the music makers, and we are the dreamers of dreams.” Life insurance lets your dream for your family keep playing, even if you’re not there to conduct the orchestra.
Practical Tips to Get Started (Without the Headache)
First, calculate your coverage. A good rule of thumb is 10 to 15 times your annual income. If you make $60,000, aim for $600,000 to $900,000. It sounds big, but term coverage for that amount can cost less than a monthly Netflix subscription.
Second, shop around. Don’t just take the first quote. Companies like Haven Life or Policygenius let you compare rates online in minutes. And skip the “final expense” policies sold on TV; they’re often overpriced for tiny payouts.
 How Does Life Insurance Work - USAA Educational Foundation
Finally, read the fine print. Policies often have exclusions for risky hobbies (skydiving, deep-sea diving) and a two-year “contestability period” where the insurer can deny a claim if you lied on your application. Yes, honesty really is the best policy—literally.
A Little Modern Wisdom
Life insurance isn’t about celebrating death; it’s about protecting life’s momentum. It’s the quiet superhero cape you put on for the people who count on you. You don’t talk about it at the office, but it’s there, holding things together.
So, next time you’re folding laundry or scrolling your phone, remember: a contract with a death benefit is just a promise made concrete. It’s not morbid—it’s mature. And maturity, these days, is a very cool thing to wear.
In daily life, take a moment to think about your “why.” That coffee you’re sipping? It’s fuel for your day. That policy you’re considering? It’s fuel for their future. One sip at a time, you’re building something that lasts—a little wisdom, a little planning, and a whole lot of love.
