Umbrella Policy: Insurance Coverage Combining Liability And Property Protection For Businesses And Individuals
Ever had that split-second thought, "What if...?" Maybe it's when you're hosting a pool party, or launching that side hustle from your garage. That tiny worry is your brain hi...
Ever had that split-second thought, "What if...?" Maybe it's when you're hosting a pool party, or launching that side hustle from your garage. That tiny worry is your brain hinting at a big gap in your protection. You've got regular insurance, sure, but what happens when a disaster goes way beyond those limits?
Think of it as an Insurance Superhero
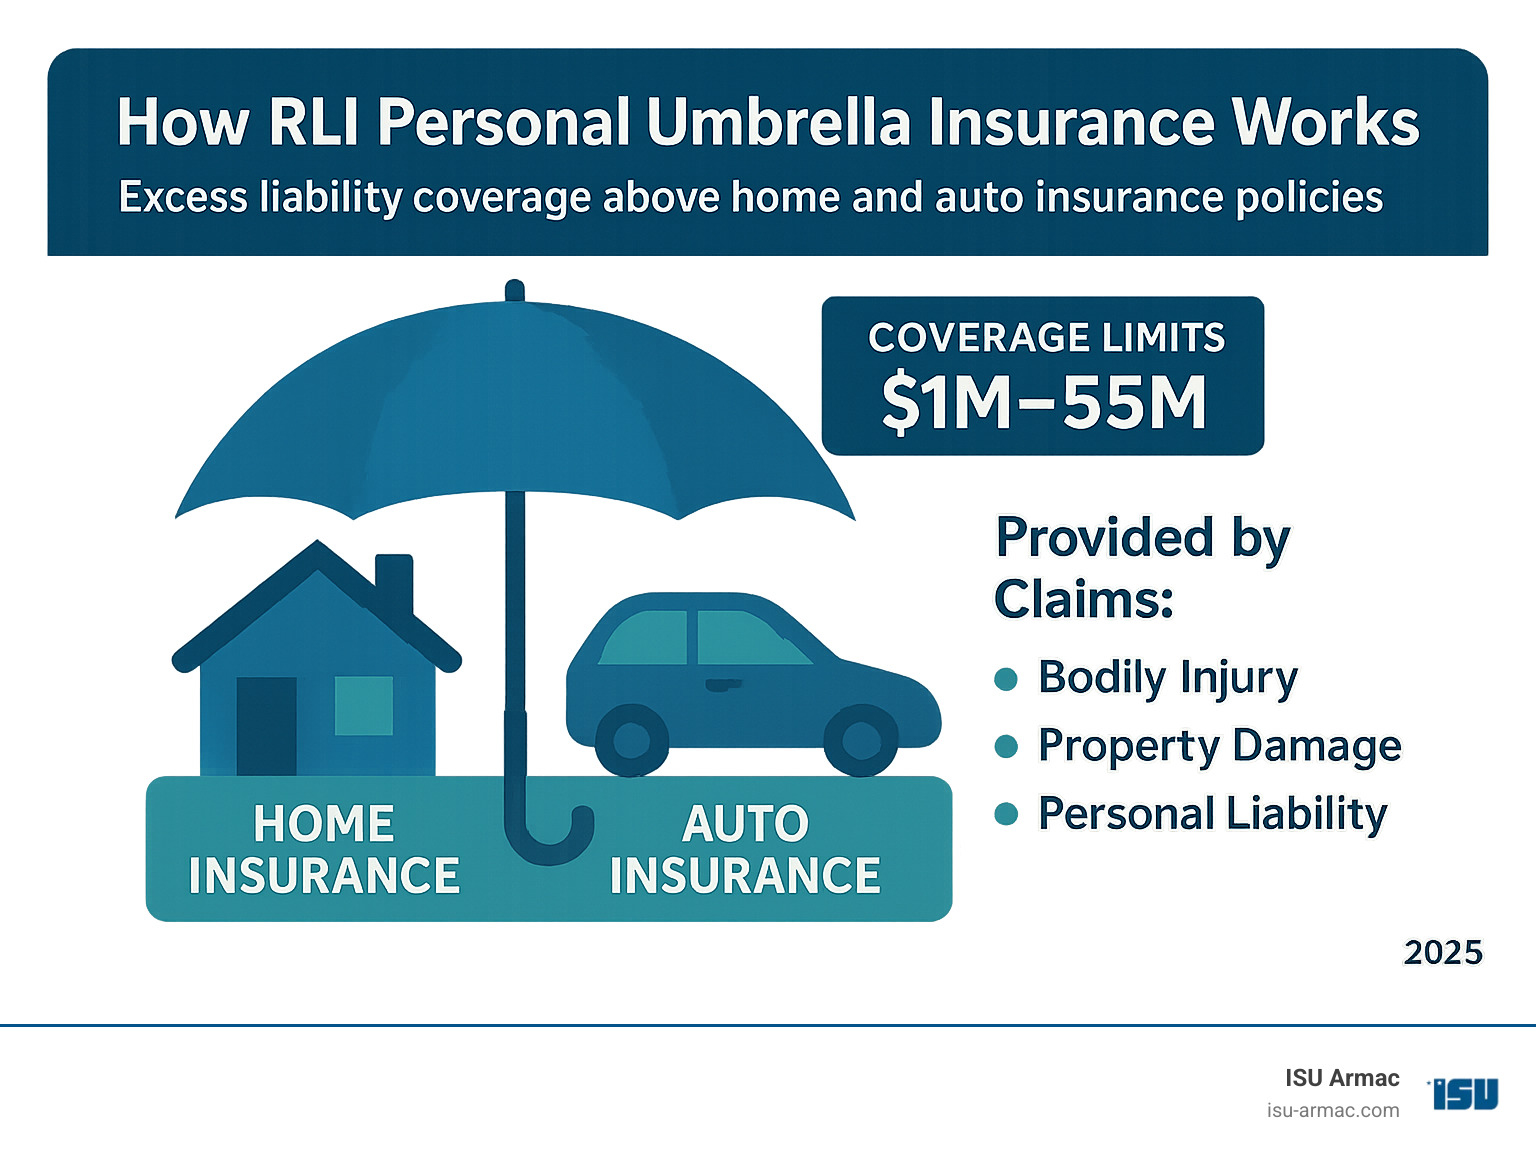
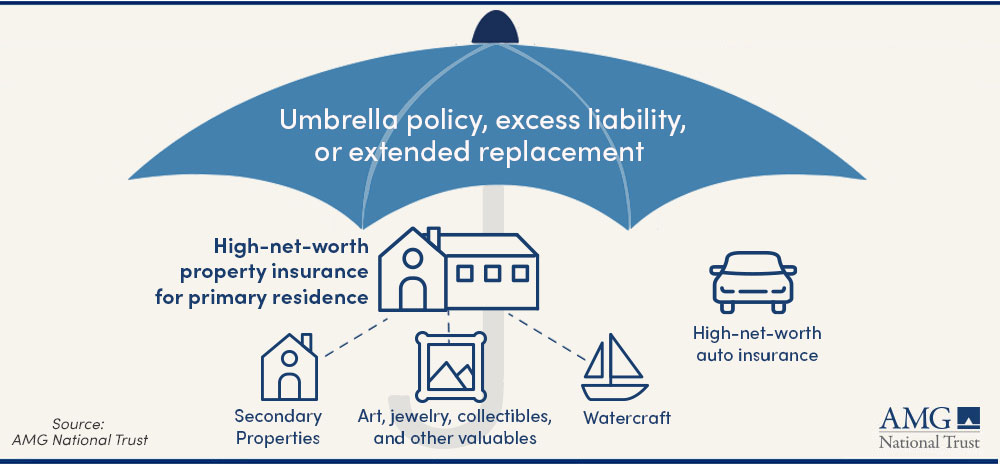
An umbrella policy isn't about, you know, umbrellas. It's a safety blanket that swoops in when your standard home, auto, or business insurance maxes out. Imagine your car insurance covers $300,000 in liability, but you accidentally cause a pile-up costing a million dollars. That's when your umbrella policy parachutes in to cover the extra $700,000. Cool, right?
It's a single policy that sits on top of your existing coverage, like a generous friend who picks up the tab after you've spent all your cash. For both businesses and individuals, it bundles together liability protection and, in some cases, even adds a layer of property coverage. Suddenly, those "what ifs" feel a lot less scary.
Must Read
Why You Might Actually Need This
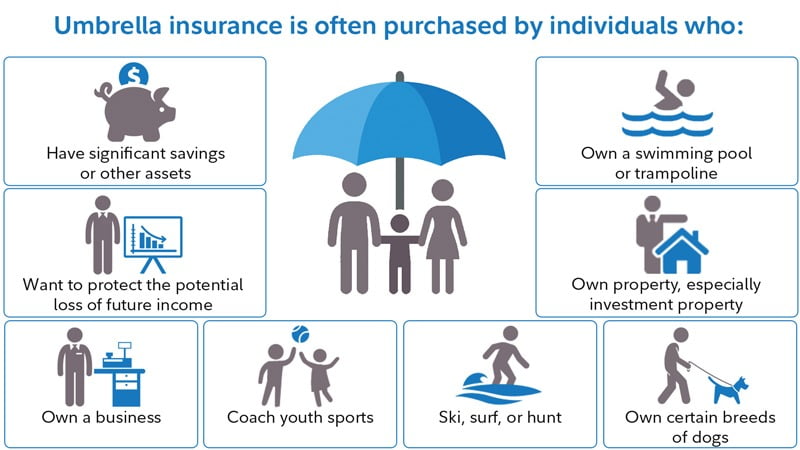
Are you a landlord with a rental property? Or maybe you've got a dog that the neighbor kids are a little too eager to pet? A single lawsuit could drain your savings and your retirement. An umbrella policy doesn't just protect your assets—it protects your future.
For businesses, the vibe is similar but amplified. If a customer slips on your wet floor and sues for medical bills plus lost wages, your commercial policy might tap out. The umbrella policy steps in, covering legal fees and settlements that would otherwise flatten your company's bank account. It's like having a financial bodyguard for your brand.
 6 Important Types of Insurance - Money Clarified
The Fun Comparison: Your Insurance as a Layer Cake
Picture a triple-decker cake. Your standard auto or home policy is the bottom layer—firm, basic, holds you up. The umbrella policy is the top layer, the one with the extravagant frosting that makes everything work together. Without it, you're just eating a dry sponge cake.
Another way to see it: think of it as a bouncer at a VIP club. Your regular insurance handles the front door, but when a rowdy lawsuit tries to crash your party, the umbrella policy bounces it out of the building. It's not just about covering costs; it's about giving you peace of mind while you binge-watch your favorite show or run your lemonade stand.
What's Actually Covered? Let's get specific.
For individuals, it typically covers liability from car accidents, dog bites, or even a guest tripping on your sidewalk. It can also extend to libel or slander—imagine a heated online review backfiring in court. For businesses, it handles things like product liability or a data breach that leads to a lawsuit. Some policies even cover legal defense costs, which are often the most expensive part of any claim.
 Property Management Insurance: Guide to Selecting the Right One
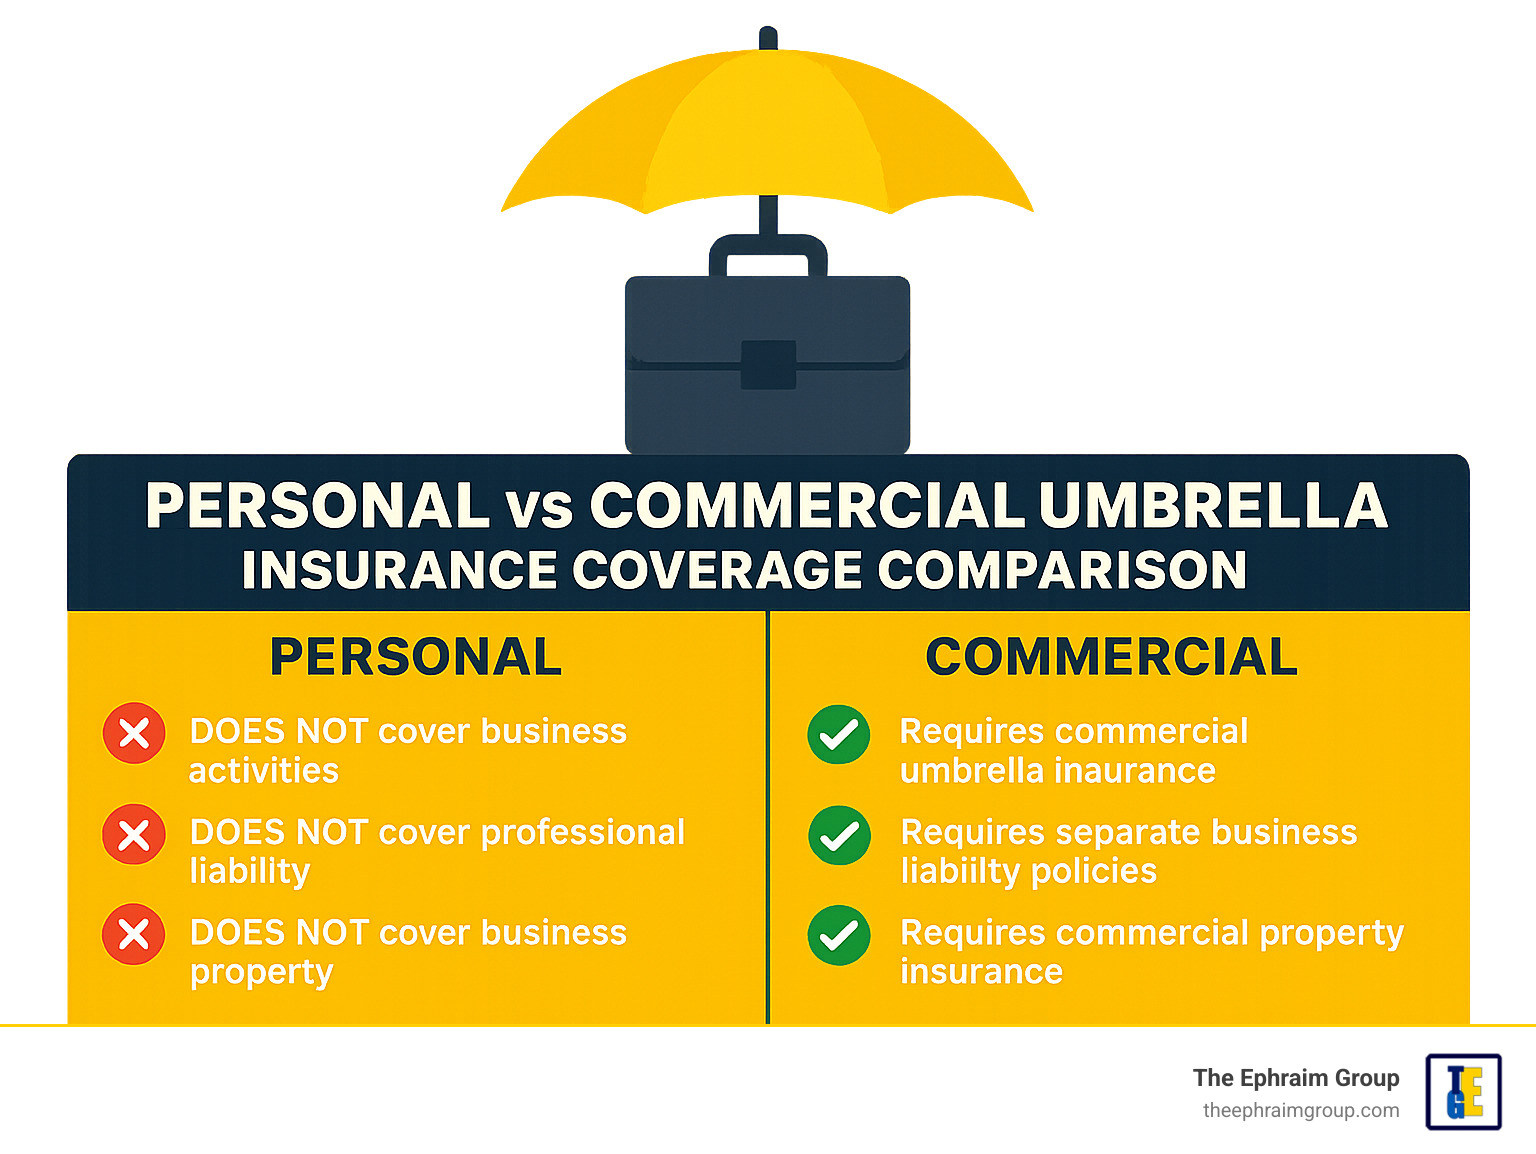
Now, it's not a magic wand for everything. An umbrella policy usually won't cover your own property damage (that's what your home insurance is for) or intentional acts of harm. But for the big, scary, "I never saw that coming" disasters? It's your best friend.
The Real Prize: Freedom from Fear
Let's be honest—we live in a lawsuit-happy world. A minor fender bender or a customer slipping on a wet floor can spiral into a six-figure nightmare. The average umbrella policy costs between $150 and $300 per year for a million dollars of coverage. That's less than a fancy dinner out. For that small price, you buy yourself a huge dose of relaxation.
 Do You Have Enough Property and Liability Insurance? – AMG National Trust
It's cool because it turns a passive safety net into an active strategy. You're not just hoping nothing bad happens; you've built a fortress. And the best part? It's one simple policy that sits on top of all your other ones—no juggling multiple forms or confusing paperwork. One umbrella, many rains.
So, Should You Get One?
Ask yourself: do you own a home? Drive a car? Have a savings account or a business that matters to you? If you answered yes to any of these, the answer is probably yes. It's like buying a fire extinguisher for your kitchen—you hope you never use it, but you'd be crazy not to have one.
Talk to your insurance agent. They can check your current limits and slap on that umbrella layer for a shockingly small amount. And when that "what if" thought creeps up again, you'll just smile—because now, you're the one with the superpowers.