Home Equity Lines Of Credit Rates
Unlocking Your Home's Potential: A Chat About HELOC Rates Ever felt like your home is a treasure trove, but you're not quite sure how to tap into its riches? Well, friend, le...

Unlocking Your Home's Potential: A Chat About HELOC Rates
Ever felt like your home is a treasure trove, but you're not quite sure how to tap into its riches? Well, friend, let me introduce you to a little something called a Home Equity Line of Credit, or HELOC for short. It's like having a magic piggy bank hidden in your walls, and today, we're going to chat about those pesky little things called rates.
What's a HELOC, You Ask?
Imagine you've just baked a batch of cookies (because who doesn't love cookies?). Now, you have two options: you can either eat them all yourself (which, let's be real, is tempting), or you can sell them to your neighbors and make a little extra cash. A HELOC is like selling those cookies - you're tapping into the value of something you already have (your home) to get a little extra spending money.
But here's the thing, rates are like the price of those cookies. You want to make sure you're not selling them for a penny when they're worth a dollar, right?
Must Read
Fixed vs. Variable Rates: The Great Debate
Now, there are two types of rates you'll hear about: fixed and variable. Fixed rates are like that one neighbor who always buys your cookies at the same price, no matter what. They're stable, reliable, but maybe not the best deal. Variable rates, on the other hand, are like the neighbor who haggles every time. They can be cheaper, but they can also change, and not always in your favor.
Think of it like this: fixed rates are like a steady paycheck, while variable rates are like working freelance. You might make more some months, but others, you'll wish you had that steady paycheck.
 Tangerine Heloc Rates at Hudson Slattery blog
Why Should You Care About Rates?
Alright, so you're thinking, "That's all well and good, but why should I care about rates?" Well, let me tell you a story. Once upon a time, there was a couple who wanted to renovate their kitchen. They took out a HELOC with a variable rate, thinking they'd save money. But then, interest rates went up, and their payments skyrocketed. Suddenly, their dream kitchen was costing them an arm and a leg.
See, rates matter because they determine how much you'll pay back. And believe me, no one wants to turn their dream project into a financial nightmare.
So, What's a Good Rate?
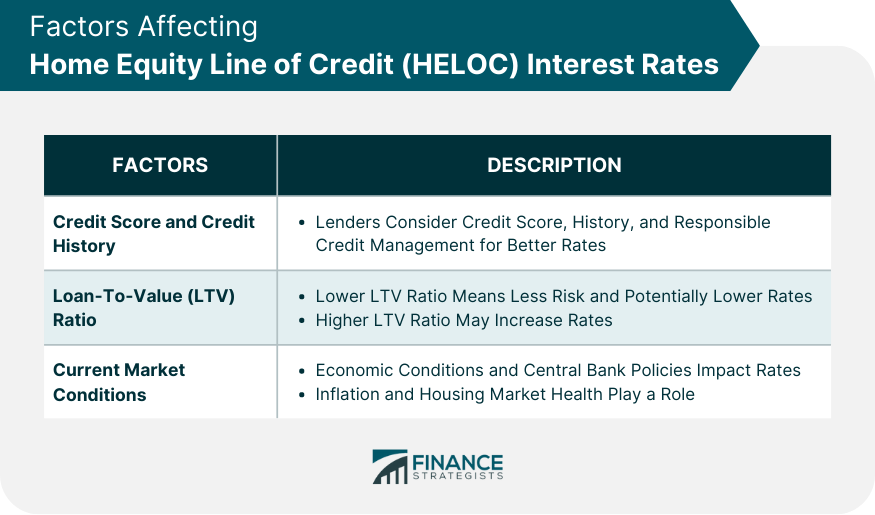
Ah, the million-dollar question. Unfortunately, there's no one-size-fits-all answer. A good rate depends on your credit score, your loan-to-value ratio, and the current market. But here's a little tip: a rate that's 2-3% above the prime rate is usually a good starting point.
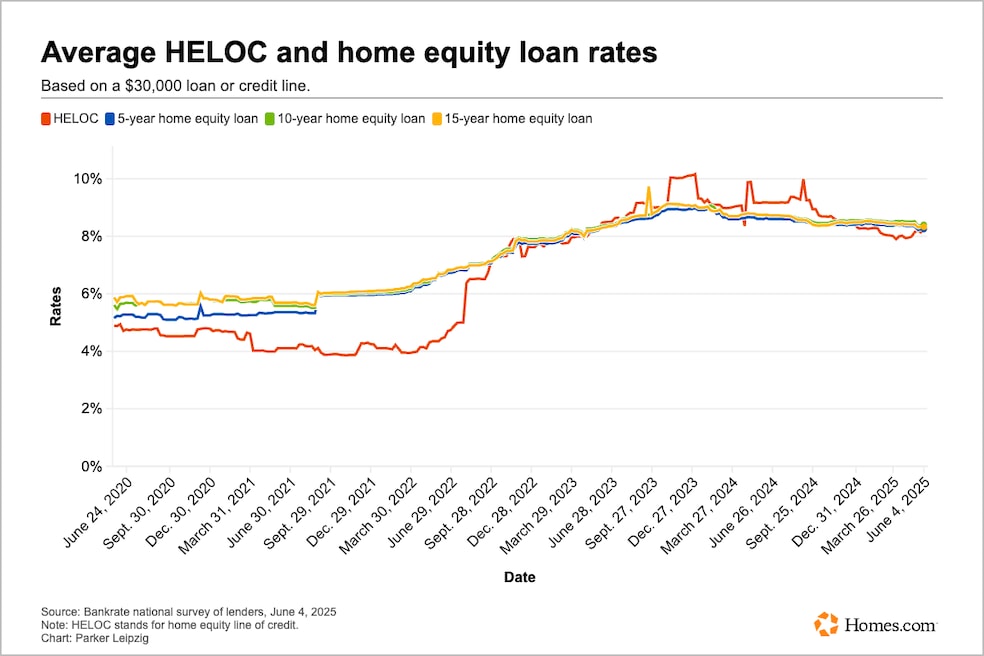 Chart of the day: Rates on home equity loans and lines of credit rise
Think of it like this: if the prime rate is 3%, then a good HELOC rate might be around 5-6%. But remember, this is just a ballpark figure. Always do your homework and compare offers.
The Bottom Line
So, there you have it, folks. HELOC rates are like the price of your cookies - you want to make sure you're getting a fair deal. They might seem confusing at first, but with a little knowledge and some careful consideration, you can unlock your home's potential without breaking the bank.
And hey, if all else fails, you can always just eat those cookies yourself. But remember, moderation is key - even with your home's equity.
